Asaan Karobar Finance Scheme 2026: Eligibility, Loan Limits, and Zero-Markup Benefits
Updated: October 26, 2026 · By Sardar Article
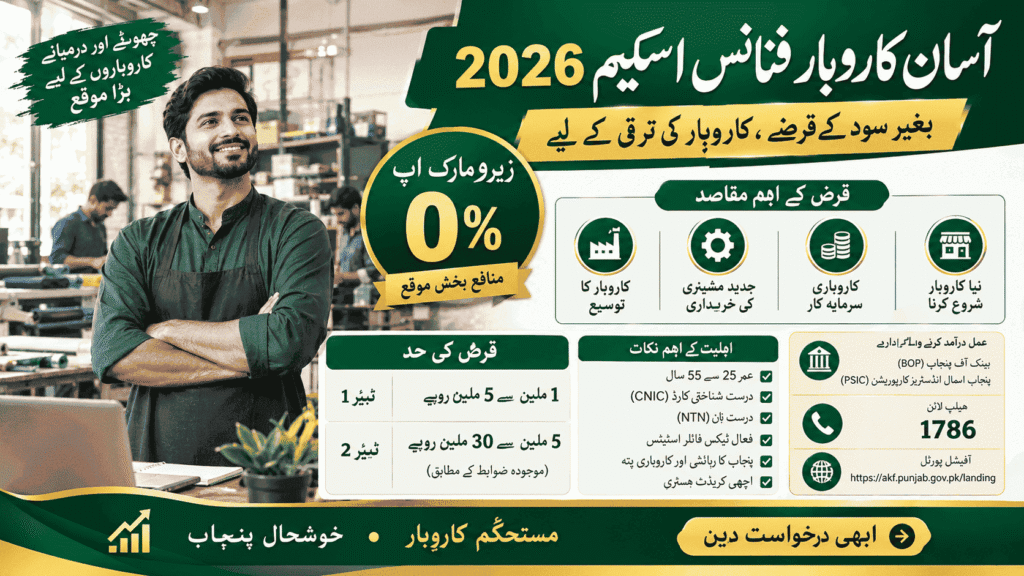
The Asaan Karobar Finance Scheme 2026 is a Government of Punjab initiative designed to help eligible small and medium-sized businesses establish, expand, and improve their operations through financing with a 0% markup rate for eligible borrowers. The scheme is implemented in collaboration with the Bank of Punjab (BOP) and the Punjab Small Industries Corporation (PSIC).
Eligible applicants may seek financing for a new business, business expansion, modernization, working capital, and certain other approved business purposes. However, approval is not automatic. Applicants must meet the applicable eligibility requirements, provide the required documents, and satisfy the bank’s assessment and security conditions.
Before applying, read the loan limits, eligibility criteria, repayment terms, fees, and additional charges explained below. Also confirm directly with the official scheme portal or helpline whether applications are currently being accepted.
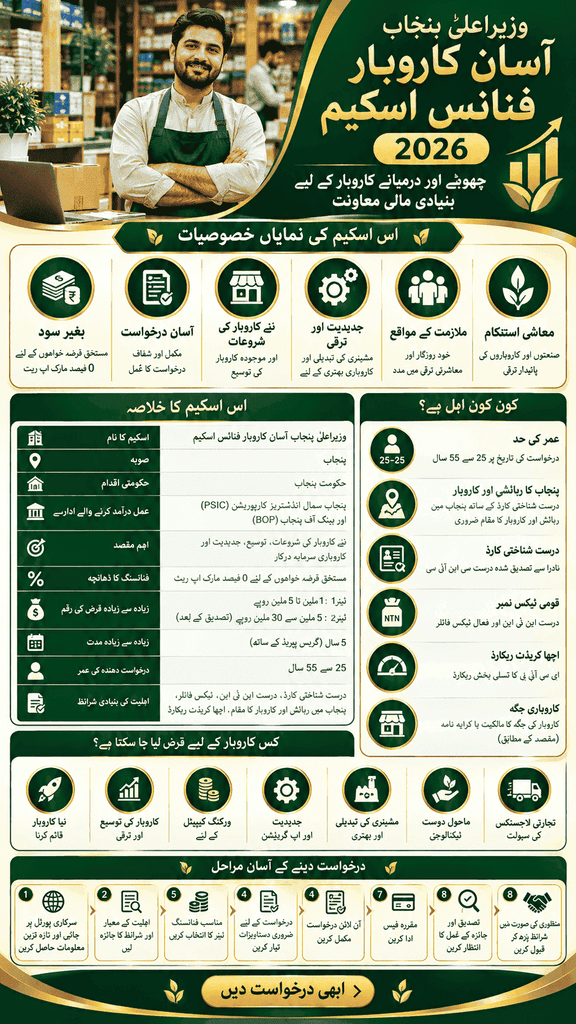
Asaan Karobar Finance Scheme 2026 – Information Table
What Is the Asaan Karobar Finance Scheme?
The Asaan Karobar Finance Scheme was introduced to improve access to business financing in Punjab. Its objective is to support entrepreneurship, encourage business growth, create employment opportunities, and help eligible small and medium-sized enterprises (SMEs) improve productivity.
The scheme is intended for eligible business owners who need financial support to start a new business or strengthen an existing one. Depending on the financing category and approval, funds may be used for business expansion, working capital, machinery replacement, modernization, and other permitted business purposes.
Although the borrower markup is advertised at 0%, the financing is not the same as a grant or free cash. Approved borrowers must repay the principal amount according to the agreed repayment schedule and may also have to pay applicable processing, insurance, legal, valuation, registration, or other charges.
Asaan Karobar Finance Scheme Loan Limits
The scheme has two main financing tiers. The amount available depends on the applicant’s eligibility, business requirements, financial assessment, and the bank’s approval.
Tier 1: Rs 1 Million to Rs 5 Million
Tier 1 is designed for eligible small enterprises seeking financing within the stated limit.
Key features include:
- Financing from Rs 1 million to Rs 5 million.
- Personal guarantee(s) rather than the standard secured-loan structure, subject to the bank’s requirements.
- A borrower markup rate of 0%.
- Repayment over a period of up to five years, including any applicable grace period.
- A processing fee of Rs 5,000 per application.
The applicant must still satisfy the scheme’s eligibility conditions and the bank’s assessment requirements. A personal-guarantee facility does not mean that every application will be approved.
Tier 2: Above Rs 5 Million to Rs 30 Million
Tier 2 is intended for eligible businesses that require a larger financing amount.
Key features include:
- Financing above Rs 5 million and up to Rs 30 million, subject to the current official tier rules.
- Secured financing.
- A borrower markup rate of 0%.
- Repayment over a period of up to five years, including any applicable grace period.
- A processing fee of Rs 10,000 per application.
The bank determines acceptable security and may require property-related documentation, valuation, legal checks, or other supporting records. Applicants should confirm the minimum eligible amount and security requirements with the Bank of Punjab before submitting an application.
Asaan Karobar Finance Scheme Eligibility Criteria
Applicants must meet the relevant scheme and bank requirements. The main criteria published by the official institutions include the following.
1. Age Requirement
The applicant must generally be between 25 and 55 years old on the date of application.
Applicants outside this age range should not assume that they qualify under the standard scheme.
2. Punjab Residency and Business Location
The applicant must be a Pakistani resident living in Punjab according to the applicable CNIC requirements, and the business must be located in Punjab.
Applicants should ensure that their identity and business information is accurate and consistent with the documents submitted.
3. Valid CNIC
A valid Computerized National Identity Card (CNIC), consistent with NADRA records, is required.
Applicants should check the validity and accuracy of their CNIC information before starting the application.
4. Valid National Tax Number
Applicants must have a valid National Tax Number (NTN). Business owners should verify that their tax registration details are correct and available for the bank’s verification.
5. Active FBR Tax-Filer Status
The scheme’s published eligibility criteria require applicants to be active tax filers with the Federal Board of Revenue (FBR).
Applicants should check their current tax status and resolve any outstanding registration or filing issues before applying.
6. Clean Credit History
Applicants must have a satisfactory credit history and a clean ECIB/credit record under the applicable rules.
Previous overdue financing, defaults, or other credit issues may affect eligibility. Meeting the basic criteria does not guarantee approval because the bank also evaluates repayment capacity and other risk factors.
7. Business Premises and Documentation
For working-capital, expansion, and balancing, modernization and replacement (BMR) financing, the official criteria require business premises to be owned or rented in the name of the applicant, partner, director, or business, as applicable.
The bank may request proof of ownership or a rent agreement and other supporting documents. Requirements can vary depending on the applicant’s business structure and the purpose of financing.
8. Business Size and Bank Assessment
The scheme is intended for small and medium-sized enterprises. The Punjab Government’s published overview identifies small enterprises by annual sales up to Rs 150 million and medium enterprises by annual sales above Rs 150 million up to Rs 800 million.
Applicants must also satisfy the applicable State Bank of Pakistan regulations and the Bank of Punjab’s underwriting requirements.
Which Business Activities Can Qualify?
The scheme’s published purposes include several types of business financing.
Interest-Free Financing: What Does 0% Markup Mean?
The scheme offers eligible borrowers a 0% markup rate. This means the borrower’s applicable financing markup is subsidized under the government-supported arrangement.
However, it is important to distinguish between zero markup and zero total cost.
Depending on the loan type and approved purpose, applicants may have to pay:
- The applicable non-refundable processing fee.
- Insurance premiums on the financed asset or security, where required.
- Legal and property valuation expenses.
- Documentation and mortgage-registration charges.
- Other applicable registration or security-related costs.
- A handling fee for certain existing-business financing cases.
- Late-payment charges if an installment becomes overdue.
The Bank of Punjab’s published scheme information states that the handling fee is generally nil for eligible new-business setup financing and 3% per annum for certain existing-business financing. It also lists an exception for qualifying climate-friendly Tier 2 business loans. Applicants should confirm how these charges apply to their particular case.
Therefore, borrowers should calculate the total cost of financing, not just the markup rate, before accepting an offer.
Processing Fees and Other Charges
The published processing fees are:
Processing Fees
Applicable fees by financing category
| Financing Category | Processing Fee |
|---|---|
| Tier 1 | Rs. 5,000 |
| Tier 2 | Rs. 10,000 |
These fees are payable according to the official application procedure and are described in the scheme information as non-refundable.
Other charges may apply according to the type of financing, security, and transaction. Before paying any fee, verify the correct amount and payment method through the official scheme portal or Bank of Punjab.
Safety advice: Do not transfer money to an unofficial agent or personal bank account on the promise of guaranteed approval. Use only the payment instructions provided by the official institutions.
Repayment Period and Grace Period
The published scheme terms provide for repayment through equal monthly installments over a period of up to five years.
The official scheme information describes the following possible grace periods:
Repayment Grace Period
Published grace period by business category
| Business Category | Published Grace Period |
|---|---|
| New Business or Startup | Up to 6 months |
| Existing Business | Up to 3 months |
A grace period is subject to the applicable scheme terms and loan approval. It should not be interpreted as a guarantee that repayment will begin only after that period in every case.
The exact installment amount, payment schedule, first installment date, and other repayment conditions should be confirmed in the bank’s approved financing documents before the applicant accepts the loan.
Late-payment charges may also apply if installments are not paid on time. Borrowers should keep sufficient funds available for their scheduled payments.
Borrower Equity and Security Requirements
The amount that an applicant must contribute personally depends on the financing tier and the purpose of the loan.
According to the published scheme information:
- Tier 1: Generally no borrower equity contribution is required, except for specified arrangements such as leased commercial vehicles.
- Tier 2: A 20% equity contribution is generally specified.
- Eligible women, transgender persons, and persons with disabilities: A reduced 10% equity contribution is listed in the scheme information for applicable cases.
- Leased commercial vehicles: A minimum 25% contribution is specified.
The bank determines the applicable contribution and acceptable form of equity under the approved financing arrangement. For Tier 2, secured financing may require property or other acceptable security, depending on the bank’s terms.
Applicants should obtain written confirmation of the required equity, security, and additional charges before proceeding.
Documents to Prepare Before Applying
The precise document list depends on the applicant, business type, and financing purpose. Applicants should prepare the following commonly relevant records and confirm the final checklist with the official portal or bank:
- Valid CNIC.
- Valid NTN and relevant FBR tax-filing information.
- Business registration details, where applicable.
- Proof of business address and ownership documents or rent agreement, where required.
- Business financial statements, income information, or bank statements, where requested.
- Details of the proposed business activity and intended use of funds.
- Business plan or feasibility information for a new business, where required.
- Property and security documents for secured financing, where applicable.
- Any additional documents requested by the Bank of Punjab or PSIC.
Do not assume that this list is exhaustive. Check the current application form for the documents required for your specific financing category.
How to Apply for Asaan Karobar Finance Scheme 2026
Applicants can use the following steps as a preparation guide. The availability of new applications must be checked on the official portal or with helpline 1786 before proceeding.
Step 1: Visit the Official Portal
Open the official scheme application website:
https://akf.punjab.gov.pk/landing
Check whether the application portal is accessible and whether new applications are being accepted.
Step 2: Review the Current Eligibility Rules
Read the latest eligibility requirements, loan tiers, fees, security conditions, and repayment terms. Make sure your age, tax status, credit history, residency, and business location meet the requirements.
Step 3: Choose the Appropriate Financing Tier
Determine whether your financing requirement falls within Tier 1 or Tier 2. Confirm the permitted amount and any required equity contribution with the official scheme information and the bank.
Step 4: Prepare Your Documents
Gather the required identity, tax, business, financial, and property-related documents relevant to your application.
Ensure that the details are accurate and that any documents requested by the bank are current.
Step 5: Complete the Official Application
If applications are open, follow the instructions on the official portal and provide the required information. Select the correct financing category and describe your intended use of funds accurately.
Step 6: Pay the Applicable Fee Through the Official Process
The published processing fees are Rs 5,000 for Tier 1 and Rs 10,000 for Tier 2. Confirm the amount, payment instructions, and refund conditions before paying.
Do not make payments to unofficial agents who promise to secure approval.
Step 7: Wait for Verification and Assessment
The relevant institutions may review your documents, tax status, credit history, business information, security, and repayment capacity.
Submitting an application does not guarantee that a loan will be approved or disbursed.
Step 8: Review the Offer Before Accepting
If your application is approved, carefully read the financing documents. Confirm the approved amount, markup arrangement, repayment schedule, equity contribution, security, fees, and any other conditions before signing.
Is the Asaan Karobar Finance Scheme Still Open in 2026?
The scheme is listed on official Punjab Government and PSIC websites, and PSIC has also published information about Phase 2 awareness activities. However, a scheme webpage or awareness event does not by itself confirm that new applications are open at this moment.
Applicants should therefore verify the current application status before preparing a payment or relying on a particular deadline.
For confirmation, use the official scheme portal:
https://akf.punjab.gov.pk/landing
You can also contact the scheme helpline at 1786 or consult the official Bank of Punjab scheme page:
https://www.bop.com.pk/view.aspx?id=3561
Do not rely on social media posts or unofficial websites that announce an application deadline without supporting official confirmation.
Frequently Asked Questions (FAQs)
1. What is the maximum loan amount under the Asaan Karobar Finance Scheme?
The standard scheme lists financing up to Rs 30 million under Tier 2. The exact amount available depends on the current tier rules, eligibility, security, and bank approval.
2. Is the Asaan Karobar Finance Scheme completely free?
No. The borrower markup is 0% for eligible financing, but processing fees and other applicable expenses—such as insurance, legal, valuation, registration, or handling charges—may still apply. Borrowers must also repay the principal amount.
3. What is the age limit for applicants?
The published standard eligibility criteria specify an age range of 25 to 55 years on the date of application.
4. Is an NTN required?
Yes. The published eligibility criteria require a valid NTN and active FBR tax-filer status, alongside other conditions.
5. Can a person apply for a new business?
New-business financing is among the stated purposes of the scheme. Applicants must meet the applicable eligibility and assessment requirements, and a feasibility report or other supporting documents may be requested.
6. What are the processing fees?
The published fee is Rs 5,000 for Tier 1 and Rs 10,000 for Tier 2. Confirm the current payment instructions through the official scheme process.
7. How can I confirm whether applications are open?
Visit the official application portal at https://akf.punjab.gov.pk/landing or call the scheme helpline at 1786. Do not assume applications are open unless the official channel confirms it.
Official Sources
For the latest information, applicants should consult these official resources:
- Punjab Government: https://www.punjab.gov.pk/asaan-karobar-finance
- Punjab Small Industries Corporation (PSIC): https://psic.punjab.gov.pk/node/178
- Bank of Punjab: https://www.bop.com.pk/view.aspx?id=3561
- Official application portal: https://akf.punjab.gov.pk/landing
- Scheme helpline: 1786
Final Words
The Asaan Karobar Finance Scheme can provide an opportunity for eligible entrepreneurs in Punjab to obtain business financing with a 0% borrower markup. However, applicants should carefully review the eligibility requirements, loan limits, repayment terms, equity contribution, and any additional charges before applying.
The most important step is to verify the current application status and exact terms through the official scheme portal, PSIC, or Bank of Punjab. Never assume that approval is guaranteed, and avoid unofficial agents who promise a loan in exchange for extra payments.
Disclaimer: Sardar Article is an independent information platform and is not affiliated with the Government of Punjab, the Bank of Punjab, or the Punjab Small Industries Corporation. Scheme rules, fees, eligibility conditions, and application availability may change. Always confirm the latest details with the relevant official institutions before making financial decisions.